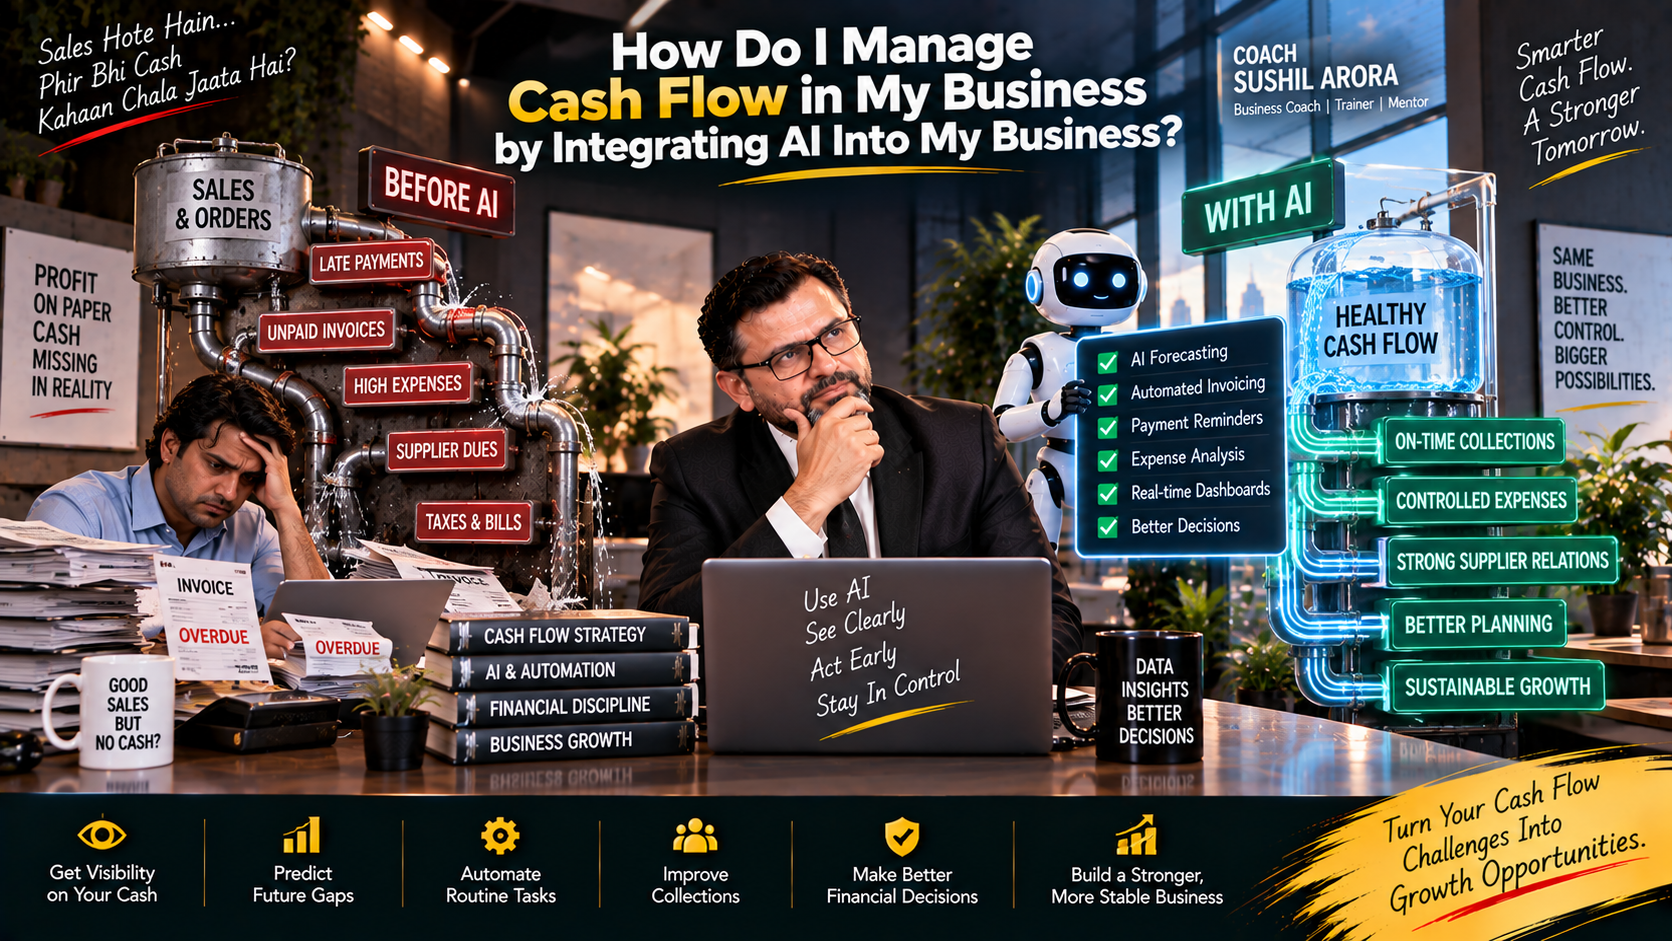
💰 “My Business Is Making Sales, So Why Am I Still Struggling With Cash?”
This is a situation many business owners find difficult to understand.
Sales are happening.
Invoices are being raised.
Customers are placing orders.
The business may even look profitable on paper.
But then salary day arrives.
Supplier payments are due.
Rent has to be paid.
Taxes and other expenses are coming up.
And suddenly the owner is asking:
“Where Is All My Cash?”
Now AI is entering this conversation too.
Business owners hear about AI forecasting, automated invoicing, expense analysis and financial dashboards, so they ask me:
👉 “Sushil Sir, Can I Use AI to Manage My Cash Flow Better?”
My answer is yes, AI can help.
But I wouldn’t begin with AI.
I would begin with your cash.
🎯 “Where Is Your Money Coming From, Where Is It Going, and Where Is It Getting Stuck?”
Until I understand those three things, adding another AI tool won’t solve the underlying problem.
💡 HOW I APPROACH AI AND CASH FLOW — SUSHIL ARORA
💰 When I work with a business owner facing cash-flow pressure, I first understand the movement of money through the business. I look at customer collections, payment cycles, recurring expenses, supplier commitments and upcoming cash needs.
🤖 Once that process is clear, I look at where AI and automation can help us see problems earlier, reduce repetitive financial work, follow up consistently and make better-informed decisions. I use AI to improve visibility and execution. I don’t ask it to replace financial judgement.
🔍 First, Understand the Difference Between Sales and Cash
This is where I would start with the owner.
Imagine you make a ₹5 lakh sale today.
Great.
But the customer has 60 days to pay.
Your sales report shows ₹5 lakh.
Your bank account doesn’t.
Meanwhile, you may need to pay your supplier in 15 days and your employees at the end of the month.
That’s a cash-flow gap.
👉 “When I Make a Sale, How Long Does It Take Before That Money Actually Reaches My Bank Account?”
That question matters.
Because a business can make sales and still struggle to meet today’s payments.
💡 A Sale Helps Your Cash Flow When the Cash Actually Arrives.
AI can help you monitor that journey.
But first, the business needs to understand it.
📊 Where I Look When Cash Flow Is Tight
I would map the movement of money like this:
Sales → Invoice → Payment Due → Collection → Cash In → Expenses → Supplier Payments → Cash Left
Then I start asking questions.
How much money is currently outstanding?
Which customers regularly pay late?
When are major payments due?
Which expenses repeat every month?
Are there months when cash requirements are naturally higher?
Are we buying inventory too early?
Are we paying suppliers before customers pay us?
How much cash do we expect to receive over the next few weeks?
🎯 “When Will Cash Come In, and When Must Cash Go Out?”
That is the basic question behind cash-flow management.
AI becomes useful when it helps the owner answer it earlier and more consistently.
1. AI Can Help You See a Cash Shortage Before It Happens
Many owners discover a cash problem when the bank balance is already low.
I don’t want to wait that long.
I would rather ask:
🔮 “What Is My Cash Position Likely to Look Like 30, 60 or 90 Days From Now?”
A basic cash forecast considers expected incoming money and expected outgoing payments.
If the business has reliable historical and current financial data, AI-supported financial software can help analyze patterns and assist with forecasting.
For example, it may help identify:
📥 Expected customer collections
📤 Recurring payments
📅 Upcoming bills
📊 Historical cash patterns
⚠️ Possible periods of cash pressure
But I would treat that forecast as a decision aid, not a guarantee.
Customers can pay late.
Sales can change.
Unexpected expenses happen.
🤖 AI Can Help You See a Possible Problem Earlier. You Still Need to Decide What to Do About It.
That extra visibility can give the owner more time to act.
2. Use AI to Help Find Patterns in Late Customer Payments
Suppose you have 200 unpaid invoices.
Looking through them manually every day isn’t a good use of the owner’s time.
I would want the business to know:
Which invoices are overdue?
How much is outstanding?
Which customers regularly pay late?
Which large payments are approaching their due date?
Which overdue accounts need attention first?
AI-supported systems can help organize and analyze this information.
Then instead of saying:
“We Have a Collection Problem.”
we can ask:
🎯 “Which Customers and Invoices Are Creating Most of the Collection Delay?”
Now we have something specific to work on.
💰 Don’t Treat All Outstanding Payments as One Number. Find Out Where the Delay Is Coming From.
3. Automate Routine Payment Reminders
This is one of the simplest places where automation can help.
Many businesses don’t have a consistent collection process.
An invoice becomes overdue.
Someone notices it a week later.
They call the customer.
Then everyone gets busy.
Another week passes.
The owner eventually asks:
“Has that payment come?”
Nobody is sure.
I would rather define the process.
⚙️ Invoice Sent → Due-Date Reminder → Overdue Reminder → Human Follow-Up → Escalation
Automation can handle some routine reminders.
AI may help draft appropriate messages or prioritize which accounts need attention.
But I wouldn’t automate every customer interaction blindly.
An important long-term customer with a genuine issue may need a person.
A disputed invoice certainly needs investigation.
💡 Automate the Routine Reminder. Keep People Involved Where Judgement and Relationships Matter.
4. AI Can Help You Understand Where Money Is Being Spent
Cash problems aren’t always caused by slow collections.
Sometimes money is leaving the business faster than the owner realizes.
Another subscription.
Extra software.
Advertising.
Travel.
Supplier increases.
Small recurring charges.
Rush purchases.
Operational expenses.
Individually, they may not look serious.
Together, they can affect cash significantly.
With properly connected financial data, AI-assisted tools can help categorize transactions and identify spending patterns for review.
Then I would ask:
🔍 “Which Expenses Have Increased, and Do We Understand Why?”
This is important.
I don’t want AI automatically deciding:
“This expense is unnecessary. Remove it.”
The tool may not understand why the business needs it.
⚠️ AI Can Find a Pattern. The Business Owner Still Needs to Understand the Reason Behind It.
5. Use AI to Help Detect Unusual Changes
Imagine your delivery expense is normally around a certain level.
This month it jumps sharply.
Would you notice immediately?
Maybe.
Maybe not.
The same can happen with:
Marketing spend.
Overtime.
Software charges.
Purchasing.
Refunds.
Payment fees.
Inventory costs.
An AI-enabled financial system may help flag unusual changes for review.
Then someone inside the business asks:
👉 “Why Did This Number Change?”
Maybe there is a perfectly reasonable explanation.
Maybe there isn’t.
The point is to investigate sooner.
🔔 I Want Technology to Bring the Exception to My Attention. I Don’t Want to Discover It Three Months Later.
6. AI Can Help With Short-Term Cash Planning
Suppose you know that over the next month:
Customers are expected to pay ₹12 lakh.
Supplier payments total ₹6 lakh.
Payroll is ₹3 lakh.
Other planned expenses are ₹2 lakh.
That gives you a starting picture.
Now imagine some customers normally pay two weeks late.
That changes the timing.
AI-assisted forecasting may help model different scenarios using the business’s available data.
For example:
📊 “What Happens if Customer Collections Are Delayed?”
📊 “What Happens if Sales Are Lower Than Expected?”
📊 “What Happens if a Major Expense Arrives Earlier?”
These scenarios don’t predict the future perfectly.
They help the owner think ahead.
🎯 Cash Planning Isn’t About Knowing the Future Exactly. It’s About Being Less Surprised by It.
7. Don’t Ignore Inventory When Looking at Cash Flow
For businesses that hold inventory, a lot of cash can be sitting on shelves.
You buy stock.
Cash leaves the bank.
But that stock doesn’t become cash again until somebody buys it and pays you.
If you buy too much of the wrong product, money can stay tied up for a long time.
I would ask:
📦 “Which Stock Is Moving, and Which Stock Is Holding My Cash?”
AI-supported inventory systems can help analyze historical demand and sales patterns.
That can support purchasing decisions.
But again, I wouldn’t allow a forecast to make major purchasing decisions without review.
Market conditions change.
Customer demand changes.
One unusual year can distort historical patterns.
💡 Use AI to Improve the Information Behind the Purchase. Keep Business Judgement in the Decision.
8. Your Supplier Payment Timing Matters Too
Cash flow isn’t only about getting customers to pay faster.
It is also about understanding when your business has to pay.
Suppose customers normally pay in 45 days.
But suppliers require payment in 10 days.
Your business has to finance that gap.
I would map those timings.
🔄 Customer Payment Cycle ↔ Supplier Payment Cycle
Then I would ask:
🎯 “Are Our Payment Terms Creating Unnecessary Cash Pressure?”
Depending on the business and supplier relationship, there may be room to discuss payment schedules or plan purchases differently.
AI can help us see the timing problem.
The owner or finance team handles the actual commercial decision and conversation.
9. AI Can Help Give the Owner a Better Daily View of Cash
I don’t want a business owner discovering the financial position only when the accountant sends a report at the end of the month.
The owner doesn’t need 100 financial metrics every morning either.
I prefer a small number of useful numbers.
For example:
💵 Current available cash
📥 Expected near-term collections
📤 Major upcoming payments
🧾 Overdue receivables
📊 Expected cash position
⚠️ Important exceptions requiring attention
AI-enabled systems may help summarize financial information and bring important issues to the owner’s attention.
📱 “What Do I Need to Know Today That Could Affect My Cash Tomorrow?”
That’s the kind of dashboard I find useful.
Not more data.
Better visibility.
10. AI Cannot Fix Bad Financial Data
This is something I would make very clear.
Suppose:
Invoices aren’t entered properly.
Expenses are missing.
Customer payments aren’t matched.
Personal and business expenses are mixed.
Inventory records are inaccurate.
Payment dates aren’t updated.
Then you connect AI.
What do you expect it to forecast?
⚠️ Bad Data Doesn’t Become Good Financial Information Just Because AI Analyzes It.
Before relying heavily on AI, I would improve the underlying financial process.
Who records transactions?
How often are accounts updated?
Who checks them?
Are categories consistent?
Is the information accurate enough to make decisions from?
🎯 Clean the Process Before Asking AI to Read the Process.
🚀 How I Would Integrate AI Into Cash-Flow Management
If you came to me and said:
“Sushil Sir, I Want to Use AI to Manage My Cash Flow Better. Where Do We Start?”
I wouldn’t start by buying software.
I would work through it in this order.
🔍 Step 1: Map How Cash Moves Through the Business
I want to know:
Where does cash come from?
How long does collection take?
Where does cash go?
Which payments are fixed?
Which are variable?
Where does cash regularly get stuck?
📊 Step 2: Fix the Basic Financial Data
Before AI, I want reliable information.
Invoices.
Collections.
Expenses.
Payment dates.
Supplier obligations.
Inventory where relevant.
If the information is poor, improve that first.
🎯 Step 3: Identify the Biggest Cash-Flow Problem
Then I ask:
“What Is Creating the Most Cash Pressure Right Now?”
Slow collections?
Unplanned expenses?
Poor forecasting?
Inventory?
Supplier terms?
Low margins?
Rapid growth consuming working capital?
Find the problem before choosing the technology.
🤖 Step 4: Choose AI or Automation for That Specific Problem
Now technology has a job.
If collections are weak, use systems to track invoices, reminders and priorities.
If forecasting is weak, improve cash forecasting.
If expense visibility is poor, use tools to categorize and review spending.
If reporting takes too long, automate routine summaries.
⚙️ Step 5: Keep Humans in the Approval Process
I would not give an AI system uncontrolled authority over important financial decisions.
Large payments.
Supplier changes.
Credit decisions.
Pricing.
Major purchasing.
Financial commitments.
These require appropriate human review.
📊 Step 6: Create a Simple Cash Dashboard
I want the owner to see what matters without opening ten reports.
Cash Available → Money Coming In → Money Going Out → Overdue Money → Expected Cash Position
Keep it practical.
🔔 Step 7: Create Alerts for Exceptions
Don’t make the owner watch the dashboard all day.
Bring attention to situations that need action.
A large invoice becomes overdue.
An expense changes unusually.
Expected cash falls below an internally chosen threshold.
A major payment is approaching.
🔄 Step 8: Review the Forecast Against Reality
At the end of the period, ask:
📈 “What Did We Expect to Happen, and What Actually Happened?”
If the forecast was wrong, understand why.
That helps improve both the process and future planning.
⚠️ The Mistake I Want Business Owners to Avoid
The biggest mistake would be thinking:
“I’ll Install an AI Finance Tool and My Cash-Flow Problem Will Be Solved.”
No.
If customers pay late because nobody follows up, you need a collection process.
If the business spends without control, you need financial discipline.
If margins are too low, you need to understand pricing and costs.
If inventory is poorly managed, you need better purchasing decisions.
If financial records are unreliable, you need cleaner data.
👉 AI Can Help You See and Manage the Problem. It Doesn’t Remove the Need to Fix the Business Process Behind It.
💡 HOW I LOOK AT AI-DRIVEN CASH FLOW — SUSHIL ARORA
💰 When I work on cash flow, I first follow the money. I want to understand when it enters the business, when it leaves and where delays or surprises are creating pressure.
🤖 Then I use AI and automation where they can genuinely help: forecasting, organizing financial information, identifying patterns, supporting collection workflows and bringing exceptions to the owner’s attention.
🎯 For me, AI should give the owner earlier visibility and better information. The financial decision still belongs to the business.
This is the difference between using AI and simply buying AI software.
Technology needs a specific job.
If I can’t explain what financial problem the tool is supposed to improve, I’m not ready to implement it.
🧠 I Want AI to Tell Me Where to Look, Not Tell Me to Stop Thinking
Imagine an AI system flags:
“Cash may become tight next month.”
That’s useful.
But my next question is:
🎯 “Why?”
Are collections delayed?
Are expenses increasing?
Is a major supplier payment due?
Are sales expected to slow?
Is too much money sitting in inventory?
The alert starts the investigation.
It doesn’t finish it.
💡 Good AI Should Help You Ask Better Financial Questions Earlier.
That’s how I would use it.
💬 Final Thoughts From Sushil Arora
If you’re asking:
“How Do I Manage Cash Flow in My Business by Integrating AI?”
Don’t begin with the AI.
Begin with the cash.
💵 Understand When Money Actually Enters Your Business.
🧾 Know Which Customers Owe You Money.
📤 Know Which Payments Are Coming Up.
📦 Understand Where Cash Is Tied Up.
🔍 Find the Biggest Source of Cash Pressure.
Then bring AI into the areas where it can reduce manual work and improve visibility.
🤖 Use AI to Help Forecast.
🔔 Use Automation to Support Timely Follow-Up.
📊 Use AI to Help Find Patterns and Exceptions.
⚙️ Automate Routine Financial Work Where Appropriate.
👤 Keep People Responsible for Important Financial Decisions.
AI should make it easier to understand what is happening.
It shouldn’t make the owner stop understanding the finances.
🎯 Your Next Step
Before integrating another AI tool, sit down with your financial information and answer:
👉 How Much Cash Is Available to the Business Today?
👉 How Much Customer Money Is Currently Outstanding?
👉 Which Customers Regularly Pay Late?
👉 What Major Payments Are Due Over the Next 30 Days?
👉 Where Is Cash Tied Up for Longer Than It Should Be?
👉 Which Expenses Have Increased Recently?
👉 How Far Ahead Can I Currently See a Cash Shortage?
👉 Which Financial Tasks Are Still Being Done Manually Every Week?
👉 Which of Those Tasks Could Be Safely Supported by AI or automation?
Then ask:
🎯 “What Cash-Flow Problem Am I Asking AI to Solve?”
If you can’t answer that clearly, don’t start with the tool.
Find the problem first.
Then choose the technology.
Then measure whether it actually helps.
💡 MY AI CASH-FLOW PHILOSOPHY — SUSHIL ARORA
💰 I believe cash-flow management starts with visibility. A business owner should understand when money is expected, when payments are due and where cash is getting delayed or tied up.
🤖 I use AI to help turn that financial information into earlier warnings, clearer patterns, better forecasts and more consistent routine processes.
🎯 But I don’t hand financial judgement over to AI. I want technology to help the owner see the problem earlier, understand it better and make a more informed decision about what to do next.
— Sushil Arora